

DailyPay On-Demand Pay
by DailyPay Inc
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
When an unexpected bill lands before payday, the difficult part is often not earning the money but waiting for the usual pay cycle. DailyPay On-Demand Pay is a finance app built around that gap: it lets eligible employees access wages they have already earned before the next scheduled payday. I see it as a timing tool rather than a general budgeting app, and that distinction matters when deciding whether it belongs on your phone.
I approached it as someone trying to make a practical choice, not as a replacement for a bank account or a long-term financial plan. The app is free to install, is rated for Everyone, and comes from DailyPay Inc. Its audience is broad enough to include anyone who wants more control over when earned income becomes available, but the value depends heavily on how your employment and payroll setup work with the service.
What to consider before relying on early wage access
The first question is simple: do you need access to money you have already earned, or do you need to borrow money? Those are not the same thing. DailyPay is designed around earned wages, so its appeal is strongest when a paycheck is on the way and the problem is the calendar. If you need a larger amount than you have earned, want to build savings, or need a long-term solution for recurring shortfalls, a conventional bank product or a structured budget may be more appropriate.
The second question is whether your employer participates in the DailyPay system. Installing the app is not the same as being able to use every part of it. In practice, the service makes sense only when your employment and payroll arrangements support access. I would check that point before planning around a transfer, because an attractive idea is not useful if your workplace cannot connect to it.
The third decision criterion is urgency. Early access can be useful for a grocery run, a utility payment, transportation, or an unexpected household expense. It is less convincing when used automatically every pay period simply because the money is available sooner. Pulling forward earned income can make today easier while leaving the next payday feeling smaller, so I would treat the app as a controlled release valve rather than extra income.
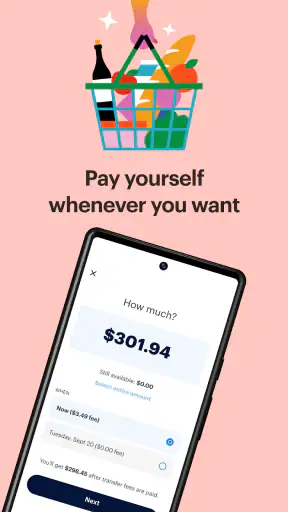
Finally, I would look closely at the total cost and timing of each transaction shown in the app before confirming it. The important comparison is not just “Can I get the money now?” but “What will I receive, when will it arrive, and what will remain for my normal payday?” Those details should guide the decision each time, especially when the expense is not genuinely urgent.
A realistic payday-gap example
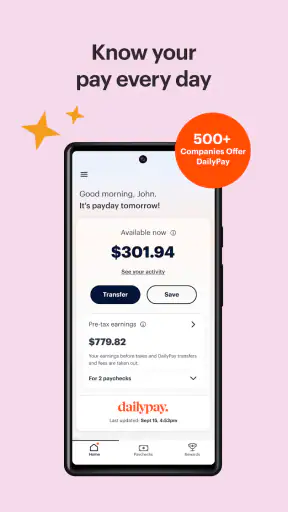
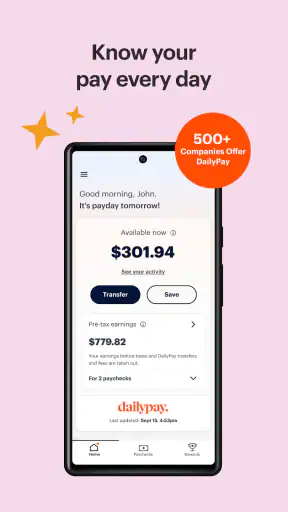
Imagine that I have worked several shifts, but my phone bill is due before the next payroll date. Instead of putting the bill on a credit card, I open DailyPay, review the amount of wages available to me, and consider taking only what covers the bill. The sensible move is to avoid withdrawing the full available balance just because it appears on screen. A smaller transfer protects more of the regular paycheck and keeps the app focused on the immediate problem.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That workflow reveals one of the app’s most useful practical lessons: the available amount is not a spending target. It is a ceiling. I would use it to solve a defined expense, write down the amount I moved, and then leave the remainder untouched. That habit turns on-demand pay into a budgeting decision instead of an impulse button.
How the app fits into everyday money management
DailyPay is best understood as a bridge between work already completed and the date when payroll normally arrives. It does not replace the need to track bills, maintain an emergency cushion, or understand the deductions from a normal paycheck. I would still keep a simple note of upcoming obligations and compare them with the next expected pay cycle.
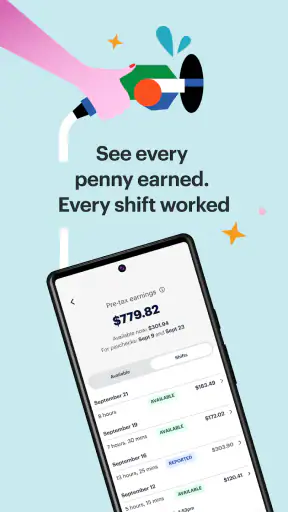
That extra step is especially important for people with variable hours. If my schedule changes from week to week, the amount available through the app may not feel as predictable as a fixed salary. I would avoid making commitments based on the highest amount I have seen and instead plan around the lower, more dependable figure. The app can improve flexibility, but it cannot make irregular income regular.
Another useful habit is to separate “earned money available early” from “money reserved for payday.” If I access funds repeatedly, I need to remember that the eventual paycheck will reflect what has already been taken out through the service. A calendar reminder or a basic spending note can prevent the common mistake of treating an early transfer as a bonus.
Where DailyPay is particularly strong
The clearest strength is timing. Traditional payroll asks me to wait for a fixed date, even when I have already completed the work. DailyPay addresses that specific frustration directly. For a worker facing a short gap between an earned wage and a due bill, that focus is more useful than a general finance app filled with charts, categories, and advice.
I also like the way the concept encourages a more precise response to a short-term problem. Instead of borrowing an arbitrary amount, I can think in terms of the expense in front of me. If the need is modest, I do not have to frame it as a large loan or use a credit card for convenience. That can make the decision feel more proportionate, provided I remain disciplined about the amount I access.
The app’s popularity suggests that this timing problem is common. It carries an average rating of 4.7 from around 238 thousand ratings, with more than 1 million installs. Those figures do not guarantee that every user will have the same experience, but they do indicate that the central idea has reached a substantial audience and is being used widely enough to attract a large body of feedback.
Another advantage is its narrow purpose. I do not need to learn an elaborate investing platform to address a payday gap. For someone who wants a straightforward way to examine earned-pay access, that limited scope can be a benefit. The app is easier to evaluate when I ask one question: does it help me manage the timing of income without encouraging me to spend more than I can comfortably absorb?
Small decisions that make a big difference
My first practical tip is to open the app before an emergency, not only during one. I would familiarize myself with the screens, account setup, and available balance while things are calm. That reduces the chance of making a rushed decision when a payment is due in a few hours. It also gives me time to understand what the app is showing instead of assuming every displayed amount is immediately suitable for withdrawal.
My second tip is to use a “bill-sized” transfer. If the expense is a specific amount, I would take only that amount or the closest sensible figure rather than emptying the available balance. This approach preserves flexibility for the rest of the pay period and makes it easier to see whether the service is actually helping.
My third tip is to review the next payday as part of every transaction decision. The question I would ask is, “Will the remaining paycheck still cover rent, food, transport, and automatic payments?” If the answer is uncertain, the correct choice may be to wait, contact the bill provider, or use a different source of short-term support. Early access is helpful only when it solves one problem without creating another.
A fourth insight is that the app may be more valuable for occasional timing mismatches than for permanent cash-flow problems. If I need early access every pay period to cover ordinary expenses, I would treat that pattern as a warning sign. The service can soften a rough week, but repeated dependence points toward a broader income, expense, or debt issue that an on-demand pay tool cannot fix.
Where a different category may fit better
The usual alternatives fall into different categories, and each solves a different problem. A bank account with an emergency fund is slower to build but generally gives greater independence once the cushion exists. A credit card may offer payment flexibility, yet it can turn a short delay into revolving debt. A personal loan is designed for larger, planned borrowing and is usually a poor match for a small expense that can be covered by wages already earned.
A budgeting app may be better if my main challenge is not payday timing but understanding where my money goes. Budgeting tools can help identify subscriptions, irregular bills, and spending patterns. DailyPay can help with access, but it should not be mistaken for a complete view of financial health. If I keep reaching for early wages because I do not know why my balance disappears, tracking and planning deserve attention first.
Employer-based savings programs may also be a better fit for someone whose priority is building a reserve. Saving a small amount from each paycheck does not provide the immediate convenience of on-demand access, but it can reduce the need to draw wages forward later. I would choose that route when the problem is recurring and predictable rather than sudden.
For someone who already has reliable savings, the app may offer little additional value. Moving money from a reserve can be simpler and may avoid the mental accounting that comes with reducing a future paycheck. In that situation, DailyPay is not necessarily the wrong product; it is simply solving a problem I may already have solved another way.
Limitations and points of friction
The most important limitation is that the experience is tied to employment and payroll eligibility. That makes it less universal than a standard banking app. A person between jobs, working outside a supported arrangement, or earning through a setup that does not connect cleanly may not find it useful. I would verify the employment connection before treating the app as part of my emergency plan.
There is also a psychological cost to convenience. Seeing earned money earlier can make it easier to spend money that was previously protected by the pay cycle. Even careful users may begin checking the available balance as if it were a normal bank balance. I think the app works best when I decide in advance what qualifies as an emergency and avoid opening it for casual spending.
Timing deserves attention as well. “Available before payday” does not automatically mean every transfer will behave like cash in my hand at the exact moment I want it. I would read the transaction details shown during the process and allow room for the payment deadline. For a bill due immediately, I would not wait until the final minute to start arranging funds.
The app also cannot remove the underlying limits of earned income. If my available wages are not enough for the expense, accessing them early will not solve the whole problem. That is where a conversation with a provider, a payment arrangement, or a different financial resource may be more realistic. DailyPay is a timing solution, not a way to increase total earnings.
Cost, switching, and the habit it creates
The app itself is free, which makes trying it less intimidating than signing up for a paid financial service. Still, I would not confuse a free download with a cost-free financial decision. The relevant cost is the transaction information presented when I choose an access method, along with the effect of receiving less through the normal payroll event. I would review those details every time rather than assuming one past experience applies forever.
Switching to DailyPay can be easy at the app level, but changing my cash-flow habits is the more significant transition. Before using it, my payday may have served as a natural spending boundary. After using it, I may need to create that boundary myself. I would keep a running record of early access and compare it with the next paycheck so the convenience remains visible rather than disappearing into everyday spending.
If I stop using the app, the main adjustment is returning to the normal payroll rhythm. That can feel restrictive at first, especially after becoming accustomed to earlier access. For that reason, I would not build rent or other essential payments around the assumption that an early transfer will always be available. A financial tool should provide flexibility without becoming the only support holding up a fixed obligation.
The current app version is 52.0.0, and it supports devices running iOS or Android version 9 and later. I would keep the application updated and use a device that receives routine security updates, particularly because the app concerns income and personal financial information. The age rating is Everyone, but that does not mean every financial decision inside it is suitable for every situation; younger users and anyone sharing a device should be especially careful with access and account privacy.
Who should use it, and who should skip it
I would recommend DailyPay to an eligible worker who occasionally faces a short gap between completing work and receiving the normal paycheck. It is particularly sensible when the expense is necessary, the amount is clear, and the next paycheck can comfortably absorb the early access. In that situation, the app offers a focused alternative to putting a small bill on a credit card or asking someone else for help.
I would be more cautious for anyone whose budget is already short every month. Early wage access may provide relief today but leave the same shortage waiting at the next payday. If the pattern is recurring, I would prioritize a full budget review, assistance with bills, a savings plan, or professional financial guidance instead of increasing reliance on the app.
I would also skip it if I need a broad financial dashboard, investment management, detailed expense analysis, or a long-term borrowing product. DailyPay is not trying to be all of those things. Its strength comes from its narrow purpose, and choosing it for a different job would lead to disappointment.
My recommendation after weighing the trade-offs
DailyPay On-Demand Pay is a useful specialist app for managing the timing of earned income. I like it most when I define the problem clearly, access only what I need, and remember that early money reduces what arrives through the regular payroll cycle. The free app, Everyone rating, and compatibility with Android or iOS version 9 and later make it approachable, while its finance focus keeps the experience centered on a practical need.
DailyPay Inc has built something that can be genuinely helpful without being a complete answer to financial stress. My recommendation is positive for eligible workers who need occasional flexibility and can maintain a clear record of each transfer. I would not recommend treating it as extra income, a substitute for savings, or a routine way to balance a permanently short budget.
In the end, I would make the decision one transaction at a time. If the app helps me cover a defined expense with wages already earned and leaves the next payday manageable, it earns a place in my financial toolkit. If it encourages me to spend ahead of every paycheck, a budget, savings cushion, or another category of financial support is the better choice. The best use of DailyPay is controlled flexibility, not permanent dependence on early access.
Pros
- Access earned wages before payday for eligible shifts.
- Can help cover unexpected expenses without using a credit card.
- Transfers are available through a simple mobile experience.
- Useful for workers with irregular hours or changing income.
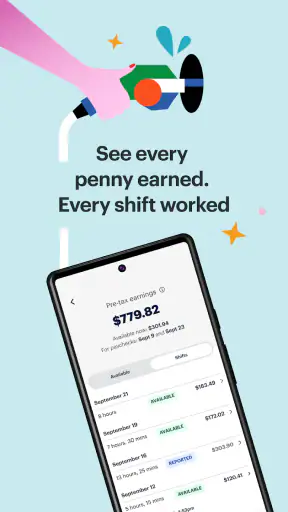
- Clear access to pay details can improve budgeting awareness.
Cons
- Availability depends on employer participation and worker eligibility.
- Instant transfers may include fees, depending on the selected method.
- Not all earned wages may be available for early access.
- Frequent withdrawals could make monthly budgeting more difficult.
- Service support and transfer speeds may vary by employer or bank.
FAQs for DailyPay On-Demand Pay
What is DailyPay On-Demand Pay and how does it work?
DailyPay On-Demand Pay is an earned wage access service that may allow eligible employees to access part of their pay before the normal payday. After connecting your account through a participating employer, the app displays available earned wages based on hours or income reported by payroll. You can request a transfer when needed, while any remaining balance is generally sent through your employer’s regular payroll schedule.
Is DailyPay available to everyone, or does my employer need to participate?
DailyPay is not normally available as a standalone service for every worker. Your employer must offer DailyPay and support the service through its payroll system. Even when a company participates, eligibility can depend on employment status, payroll information, completed shifts, and other employer-specific rules. Check the app or ask your human resources department to confirm whether you qualify and when access becomes available.
How much money can I access before payday?
The amount available through DailyPay is usually only a portion of wages you have already earned, rather than your entire expected paycheck. Your available balance can change as shifts are reported, payroll data is updated, taxes and deductions are considered, and your employer applies its own limits. The app should show the amount available before you confirm a transfer, so review it carefully.
Are there fees for using DailyPay On-Demand Pay?
DailyPay may offer different transfer options, and fees can depend on the speed of delivery, the destination account, and your employer’s arrangement. Some standard transfers may be free, while faster transfers can involve a charge. Because pricing and available options may change, review the fee displayed on the confirmation screen before submitting a request. Also remember that early access can affect your next regular paycheck.
How quickly will I receive a DailyPay transfer, and what happens to my payday check?
Delivery time depends on the transfer method you select and the receiving bank or debit card. An instant option may arrive sooner but can include a fee, while a standard option may take longer. Any amount you access early is deducted from the paycheck processed later, so your normal payday deposit will generally be smaller by the amount already received, subject to payroll adjustments.

DailyPay On-Demand Pay
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@dailypay.com, visit https://www.dailypay.com, or review their https://www.dailypay.com/privacy.










